So managing your money sounds easy, right? Until it’s your real life: with a mortgage or rent to pay, your credit cards to clear, food to buy, and your subscriptions (which might or might not be of use!) to manage, along with planned savings and plans – it rapidly becomes almost impossible.
That is where The Balance Money.com, commonly known as The Balance Money, can be useful. The personal finance website covers topics like budgeting, managing debt, saving, investing, financial planning, credit, and daily money issues. Its “budgeting” section, for instance, describes how to balance your income and expenses, and topics like emergency fund, net income, fixed expenses, and compound interest are introduced.
They approached the personal finances issue from a “Money you need to know as much about as an accountant or investor might, but approached from a way that doesn’t sound quite like the accounting firm,” in the sense that readers learn the why behind choices rather than just the what to do.
Table of Contents
What Is The Balance Money.com?
Balance Money.com is a source of personal finance information that posts useful and informative articles, guides, how-to pages, calculators, and all-round resources on managing money.
The site covers much more than the most basic topics of money management. Budgeting, debt management and repayment, credit terms, savings accounts, retirement plans, comparing and choosing financial products, investment theories-all these topics and much more are covered.
One of the most useful features of the site is its definitions section. Financial matters can easily be understood if the terms involved are easily explained. Terms like “net worth,” “compound interest,” “collateral,” “discretionary income,” and “fixed expenditures” have clear, unique meanings, and understanding their meaning is key in financial decision-making.
For example, The Balance describes net income as profit available after taxes and some before-tax additions. The Balance’s description of compound interest is interest earned on original capital plus already earned interest.
This type of definition is beneficial for beginners since it begins with the language of finance.
What Does The Balance Money Cover?
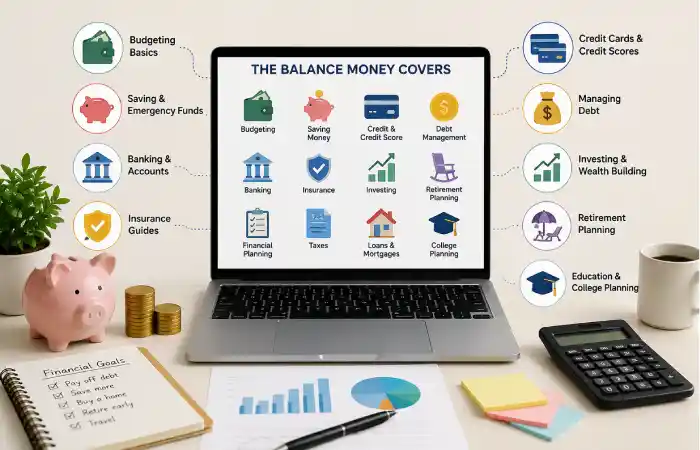
The Balance Money is broad rather than narrowly focused on one financial product. Readers can move from basic budgeting questions to more advanced subjects as their financial knowledge develops.
Common areas include:
- Budgeting and household expenses
- Saving money
- Emergency funds
- Credit cards and credit scores
- Debt repayment
- Loans and borrowing
- Investing
- Retirement planning
- Personal financial planning
- Banking
- Insurance
- Taxes and financial obligations
- Making and managing money
- Financial terminology
The website also provides guides and resources designed around specific problems. Its credit-card debt material, for example, discusses debt-reduction planning, balance transfers, personal loans, spreadsheets, and calculators.
This makes the site useful at different stages of a person’s financial life.
Understanding the Main Financial Concepts
Budgeting
Budgeting is the process of planning how your income will be used before you spend it.
A budget does not necessarily mean cutting out everything enjoyable. A good budget simply gives each dollar a purpose.
The basic calculation is straightforward:
Income – Expenses = Available funds to save, invest, or repay debt in excess of normal payments
The issue becomes apparent once the disparity between income and expenses is noticeable. After a person realizes there is an issue, they can choose one of the above options. Budgeting resources within The Balance motivate readers to understand their income and expenses, and to monitor their spending rather than estimate it.
Emergency Fund
An emergency fund is money reserved for unexpected financial problems.
A broken vehicle, sudden home repair, unexpected bill, or temporary loss of income can put pressure on a household that has no cash reserve.
An emergency fund is therefore less about making money and more about creating financial breathing room.
Net Worth
Net worth is the value of what you own minus what you owe.
The formula is:
Assets − Liabilities = Net Worth
If someone owns a home, vehicle, investments, and savings, those are generally assets. Credit-card balances, loans, and other obligations are liabilities.
Net worth can be more informative than simply looking at a bank balance because it gives a broader picture of financial position.
Compound Interest
Compound interest is one of the most important ideas in personal finance.
If money earns interest and that interest remains invested, future returns can be calculated on both the original amount and accumulated interest.
This can work in your favor when saving and investing. However, compounding can also make expensive debt grow when balances remain unpaid.
That is why understanding interest is essential before borrowing money.
The Balance Money.com vs. Other Personal Finance Resources
Different financial websites serve different purposes. Some concentrate heavily on investing, others focus on budgeting apps, while some are designed around financial news.
The Balance Money takes a broader educational approach.
| Resource Type | Main Purpose | Best For |
| The Balance Money | Personal finance education and practical guides | Beginners and everyday money decisions |
| Investment-focused websites | Markets, stocks, funds, and investing | Investors seeking market information |
| Budgeting apps | Expense tracking and financial organization | People who want automated tracking |
| Bank websites | Banking products and account information | Existing or prospective customers |
| Financial advisors | Personalized financial guidance | People needing individual planning |
The important distinction is that an educational website and a financial advisor are not the same thing. An article can explain how a Roth IRA works, for example, but it does not automatically know a particular reader’s income, tax position, family situation, risk tolerance, or financial objectives.
How The Balance Money Can Help Beginners
Personal finance becomes much less intimidating when large subjects are broken into smaller questions.
Instead of asking:
“How do I become financially successful?”
a beginner can ask:
- How much money comes into my household each month?
- Where does that money go?
- Which expenses are essential?
- How much debt do I have?
- Do I have emergency savings?
- What financial goals matter most?
- What should I learn before investing?
- Which financial decisions require professional advice?
This approach turns an overwhelming subject into a series of manageable tasks.
The Balance Money’s educational structure supports this style of learning by providing individual explanations and guides rather than requiring readers to understand every aspect of finance at once.
Debt Management: An Important Part of Personal Finance
Debt is not automatically good or bad. Its cost depends on the type of debt, interest rate, repayment terms, and the reason for borrowing.
However, high-interest revolving debt can become particularly expensive because interest continues to accumulate while a balance remains unpaid.
The Balance has published detailed resources on credit-card debt reduction. One of its guides recommends first establishing how much is owed, understanding spending habits, and then choosing an appropriate repayment strategy. It also discusses approaches such as the debt snowball and debt avalanche methods.
The difference is simple:
- Debt snowball: generally focuses on paying the smallest balance first.
- Debt avalanche: generally prioritizes the debt with the highest interest rate.
The snowball method can provide psychological motivation because smaller balances disappear faster. The avalanche method can potentially reduce interest costs when followed consistently.
Neither method is universally perfect. The right approach depends on the person’s circumstances and ability to stay committed.
Saving vs. Investing
Saving and investing are related, but they are not identical.
Saving generally means putting money aside for future use, often with an emphasis on accessibility and preserving the principal.
Investing means putting money into assets with the expectation of earning a return, while accepting some level of risk.
A useful way to think about the difference is purpose.
Money needed soon may belong in a relatively accessible savings vehicle. Money intended for a long-term goal may have a different role and risk profile.
The key lesson is that investing should not be treated as a shortcut to quick wealth. Understanding risk, time horizon, fees, diversification, and personal objectives matters.
What Makes The Balance Money Useful?
One noticeable feature is its effort to explain financial concepts in everyday language.
For example, the site’s budgeting resources do more than provide a generic budgeting definition. They discuss practical subjects such as emergency funds, fixed expenses, discretionary income, and ways to organize spending.
Another useful feature is the presence of practical resources. The site’s debt materials have included calculators, worksheets, spreadsheets, and explanations of different repayment strategies.
For someone who prefers learning by doing, these resources can be more useful than reading a long theoretical explanation.
Is The Balance Money a Bank?
This is an important distinction because the name can be confusing.
The Balance Money website should not automatically be confused with Balance Money, a separate financial technology company.
Balance Money, the fintech company, has described itself as a digital banking service designed to help users organize their money and manage spending. Its announcement stated that Balance Money was a financial technology company rather than a bank, with banking services provided through a partner institution.
The Balance Money website, meanwhile, is primarily associated with personal finance education and publishing.
When researching financial services online, checking the exact domain and company name is always worthwhile.
Advantages and Limitations
Advantages
- Broad coverage of personal finance topics
- Beginner-friendly explanations
- Definitions of important financial terms
- Articles covering everyday financial decisions
- Resources for budgeting and debt management
- Practical calculators and worksheets in some areas
- Useful starting point for financial research
Limitations
- General financial information cannot replace personalized advice
- Some financial topics can change as laws, rates, and products change
- Readers should verify important details with official sources
- Investment articles should not be interpreted as guaranteed financial outcomes
- A general guide cannot account for every individual’s circumstances
This last point is especially important. Personal finance is personal for a reason.
How to Use The Balance Money Effectively
The best way to use a financial education website is not to read dozens of articles randomly. Start with the financial problem you are actually trying to solve.
If your biggest issue is spending, begin with budgeting.
If debt is the problem, learn about interest rates and repayment strategies.
If you have built savings, start learning about investing and retirement planning.
If you are preparing for a major purchase, research loans, credit, affordability, and associated costs.
Before you do the digging, another idea that will assist: You’ll probably find it easy to translate information if you know the numbers: Your income for the month, critical expenses, your loans outstanding plus their interest rates, your savings balance, and your goals for the long term.
Final Thoughts
To put Balance Money.com best, think of it as a financial education website instead of a generic financial plan. It helps simplify complex money ideas to teach readers where they can start with the basics of budgeting, saving, paying off debt, investing, or planning their finances.